Gold IRA home storage rules govern the custody and storage of physical precious metals held within an Individual Retirement Account (IRA). Federal tax law requires IRA assets to comply with Internal Revenue Service (IRS) custody rules, prohibited transaction restrictions, and applicable account requirements. Physical gold held through an IRA differs from gold purchased and owned personally outside a retirement account. The account structure determines how the metals are owned, administered, and distributed under federal tax law. Understanding the applicable requirements helps investors assess storage arrangements before purchasing precious metals.
A home storage Gold IRA is marketed as a way to keep IRA owned gold at a personal residence. Legal compliance depends on the account structure, the custodian’s role, ownership arrangements, and applicable federal tax law. Personal possession of IRA owned metals raises concerns about trustee requirements and potential prohibited transactions. Eligible metals must satisfy applicable purity standards and other statutory conditions to qualify for IRA investment. Approved depository arrangements, custodian fees, Roth IRA requirements, and potential tax consequences also affect the legality and cost of holding precious metals through an IRA. Reviewing the applicable rules and obtaining independent tax or legal advice helps investors assess a proposed arrangement before transferring funds or purchasing gold.
What Is a Home Storage Gold IRA?
A home storage Gold IRA is an arrangement marketed as allowing IRA owned precious metals to be stored at the account holder’s residence. The label alone does not establish compliance with IRS rules, since IRA assets remain subject to custody requirements and restrictions on prohibited transactions. Physical gold owned personally outside an IRA differs from gold held inside an IRA. Personal gold belongs to the owner directly, whereas IRA assets must remain within the applicable retirement account structure to preserve tax advantages. Improper personal possession of IRA owned metals risks being treated as a taxable distribution or prohibited transaction, depending on the circumstances. The IRS requires IRA trustees or custodians to maintain control of retirement assets under applicable federal tax rules. A qualified depository provides secure storage, account documentation, and metal inventory records that support proper IRA administration.
How Does a Home Storage Gold IRA Arrangement Work?
A home storage Gold IRA arrangement involves establishing an IRA, funding the account, purchasing eligible precious metals, and arranging storage. Promotional claims about home storage do not guarantee compliance with federal tax law. IRS custody requirements and prohibited transaction rules determine whether the arrangement qualifies for favorable retirement account tax treatment.
Ready to Protect Your Retirement?
Request your free State-Specific Gold IRA information kit and take the first step toward securing your financial future with precious metals.
Free Gold IRA GuideTo know how a Home Storage Gold IRA arrangement works, follow the steps below.
- Establish an IRA. Open a self directed IRA through a qualified trustee or custodian. The account must satisfy the requirements under Internal Revenue Code Section 408.
- Fund the account. Transfer eligible retirement funds or make permitted contributions under applicable IRS rules. Improper transfers risk taxes or penalties.
- Purchase eligible metals. Direct the IRA to acquire qualifying gold bullion or approved coins. Internal Revenue Code Section 408(m)(3) establishes exceptions to the general restrictions on collectibles.
- Arrange metal storage. Promotional providers sometimes propose storing IRA owned gold at the account holder’s residence. IRS Publication 590 B states that qualifying coins must remain in the possession of the IRA trustee or custodian, and personal possession results in treatment as a distribution.
- Verify legal compliance. Review the custody structure, ownership documents, and prohibited transaction rules before accepting a home storage arrangement. Improper use of IRA assets risks loss of IRA status and taxable consequences.
Can You Legally Hold Physical Gold in an IRA at Home?
Yes, physical gold qualifies for IRA investment when the account, metals, and custody arrangements satisfy federal tax requirements. Permission to invest in physical gold through an IRA does not automatically permit personal storage at home. Internal Revenue Code Section 408 establishes trustee requirements, and violations risk taxable distributions or other tax consequences. The ruling in McNulty v. Commissioner (2021) illustrates the risks of personally possessing IRA owned gold coins. A qualified custodian and tax professional provide guidance on compliant storage arrangements and applicable reporting obligations.
How Much Will Your Gold IRA Really Cost?
See exactly how much you'll pay in setup, annual, and storage fees. Get personalized company recommendations based on your investment amount and retirement timeline.
Calculate My Total FeesWhat Rules Apply to Home Storage Gold IRAs?
Home storage Gold IRA compliance depends on federal tax law, qualifying precious metals, trustee responsibilities, personal possession, and account documentation. Internal Revenue Code Sections 408 and 4975 establish key requirements and restrictions. Noncompliance risks taxable distributions, additional taxes, or loss of IRA tax benefits. Proper account administration requires eligible assets, compliant custody arrangements, and accurate transaction records.
The rules that apply to Home Storage Gold IRAs are listed below.
- Custodian Requirements: Section 408(a) identifies the trustee requirements for qualifying IRAs. A self directed account does not automatically authorize personal custody of IRA owned metals.
- Eligible Metals: Section 408(m)(3) provides exceptions for specified coins and qualifying gold, silver, platinum, and palladium bullion. Eligibility depends on the statutory conditions.
- Storage and Possession: Qualifying bullion must satisfy the applicable trustee possession requirement. Personal storage of IRA purchased metals creates a serious risk of taxable distribution treatment.
- Prohibited Transactions: Section 4975 restricts specified transactions involving an IRA and disqualified persons. The legal consequences depend on the transaction and applicable statutory provisions.
- Tax Consequences: Improper personal possession of IRA assets risks taxation as a distribution, plus applicable penalties. McNulty v. Commissioner illustrates the consequences of home storage.
- Documentation: Account statements, purchase invoices, ownership records, and storage documents help establish the account’s structure. Documentation alone does not cure a failure to meet federal custody requirements.
What Storage Requirements Apply to Physical Gold in an IRA?
The storage requirements that apply to physical gold in an IRA include eligible trustee custody, compliant possession, and accurate account documentation. Internal Revenue Code Section 408 requires qualifying IRA assets to follow applicable trustee and custody rules. Eligible gold bullion must meet statutory purity standards to qualify for IRA investment. A personal home safe does not automatically satisfy federal custody requirements. A qualified custodian helps maintain proper asset records and account administration. A tax professional evaluates the proposed arrangement and identifies potential tax consequences. Verification before purchasing metals reduces the risk of noncompliance and unexpected tax liabilities.
Don't Pay More Taxes Than You Have To
The wrong Gold IRA choice could cost you thousands in unnecessary taxes. See exactly how much you'll pay in taxes with a Traditional vs. Roth Gold IRA. Compare both options side-by-side based on your age, income, and retirement timeline.
Can You Keep Gold IRA Metals at Home?
No, personal storage of IRA purchased gold presents serious tax risks under the reasoning applied in McNulty v. Commissioner, 157 T.C. No. 10 (2021). The U.S. Tax Court treated the gold coins held at home as taxable IRA distributions, despite the use of an IRA funded limited liability company. The court emphasized the taxpayer’s physical possession and control of the coins. The ruling demonstrates that an LLC structure does not automatically preserve IRA tax benefits when the account holder takes personal custody of retirement assets. Legal distinction. Personal ownership of gold outside an IRA differs from holding IRA assets at home. Personally owned gold remains outside the retirement account, whereas IRA purchased metals remain subject to applicable federal tax requirements.
What Are the Tax Consequences of Taking Possession of IRA Owned Gold?
Taking personal possession of IRA owned gold without following applicable distribution and custody rules risks taxable distribution treatment. The fair market value of the gold may be included in taxable income, depending on the account type and circumstances. An additional 10% tax applies to certain early distributions before age 59½, unless an exception applies. Improper possession may jeopardize the IRA’s tax advantaged status, depending on the transaction and applicable IRS rules. A properly processed in kind distribution differs from unauthorized personal possession because the distribution follows applicable IRA procedures and tax reporting requirements.
What Are the Gold IRA Custodian and Depository Requirements?
Gold IRA Company Comparison Checklist
Before choosing a Gold IRA company, use our comprehensive checklist to compare fees, reputation, storage options, and customer service ratings.
Download ChecklistThe Gold IRA custodian and depository requirements include eligible account administration, compliant metal storage, accurate transaction records, and applicable tax reporting. Internal Revenue Code Section 408 establishes requirements for IRA trustees and qualifying assets. Custodians administer retirement accounts, process transactions, and maintain account documentation. Precious metals depositories store qualifying bullion and maintain inventory records. Investors need to verify custodian eligibility, storage arrangements, and applicable fees before purchasing metals. Proper coordination supports compliance with federal retirement account rules. The account administration responsibilities fall under a Gold IRA Custodian.
What Does a Gold IRA Custodian Do?
A Gold IRA custodian administers retirement accounts, processes purchases, records transactions, handles transfers, manages distributions, plus submits required reports. The custodian oversees account records rather than selling metals or operating the storage facility. A metals dealer supplies qualifying bullion, whereas a depository provides physical storage under the approved arrangement. Account holders review fees, transaction procedures, reporting practices, plus custody arrangements before selecting a provider.
What Is a Gold IRA Depository?
A Gold IRA depository is a secure facility that stores precious metals under an applicable retirement account custody arrangement. Depositories maintain inventory records and follow storage procedures established under their agreements with custodians. Investors need to assess facility qualifications, security controls, insurance coverage, reporting practices, and coordination with the IRA custodian. Insurance terms require review because coverage limits and exclusions vary by provider. Clear storage agreements help establish how metals are identified, protected, and returned when an authorized distribution occurs.
How Much Do Gold IRA Storage Fees Cost?
Reserved for Portfolios of $500K or More
Your portfolio qualifies you for an exclusive one-on-one web conference with a senior precious metals advisor, priority service, and direct access to strategies reserved for our most valued clients.
Request Your Exclusive GuideGold IRA storage fees vary by custodian, depository, account value, storage method, and fee structure. Published 2026 schedules show annual storage charges ranging from [$100 to $225] for many flat fee arrangements, with segregated storage frequently costing more. Additional expenses include account setup, annual administration, transaction processing, transfers, and account closure. Some providers combine storage charges with custodian fees, making the total cost less obvious. Investors need to compare the complete fee schedule before opening an account. Written fee disclosures help identify recurring charges, account minimums, and additional costs.
How Do Segregated and Non Segregated Gold IRA Storage Differ?
Segregated storage keeps an account holder’s specific coins or bars separate from other customers’ metals. Non segregated storage, also known as commingled storage, groups compatible metals together while maintaining separate ownership records. Segregated storage typically carries higher annual fees, depending on the provider’s agreement. Non segregated storage costs less under some arrangements, although the exact metals returned depend on contractual terms. Storage agreements establish identification procedures, access arrangements, insurance coverage, fees, and return conditions. Reviewing the agreement clarifies whether the original coins or bars must be returned following an authorized distribution.
Which Gold Coins and Bars Are Approved for an IRA?
Your Complete Gold IRA Beginner's Guide
No confusing jargon. No pressure. Just clear answers about how Gold IRAs work, what they cost, and whether they're right for your retirement. Get the facts before you invest.
Get Your Free Starter GuideIRA eligible precious metals must satisfy Internal Revenue Code Section 408(m)(3), including applicable coin specifications, bullion purity standards, and trustee possession requirements. Not every collectible coin or gold bar qualifies for tax advantaged IRA treatment.
The gold coins and bars approved for an IRA are listed below.
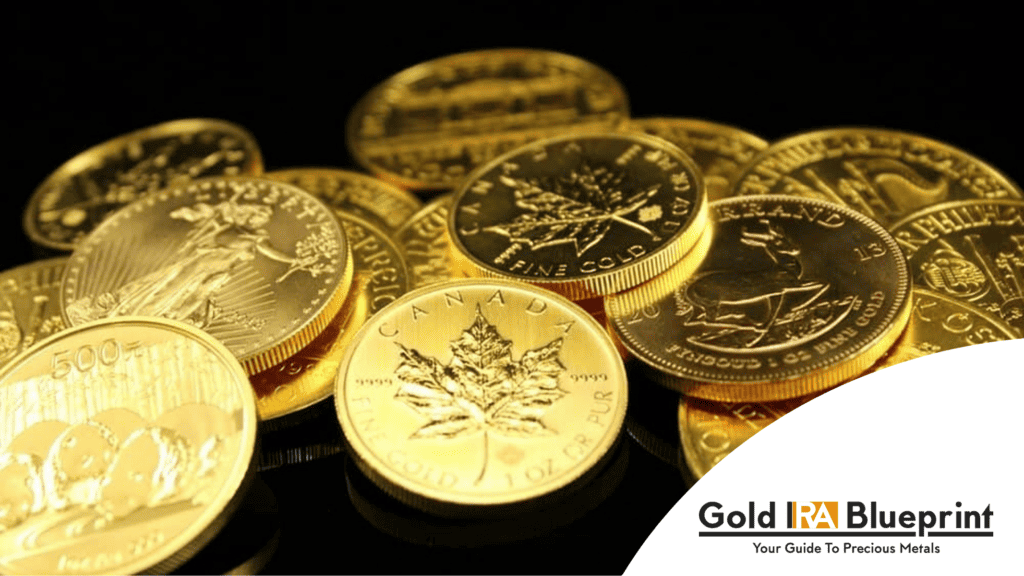
- Eligible Gold Coins: Certain U.S. gold coins qualify under statutory exceptions, including American Gold Eagle coins. Other coins require assessment under the applicable statutory provisions.
- Eligible Gold Bullion Bars: Gold bullion must meet the applicable minimum fineness standard of 99.5% purity. A qualifying trustee must maintain physical possession under the statutory requirements.
- Other Precious Metals: Silver, platinum, and palladium bullion qualify when applicable purity standards and custody requirements are met.
- Collectible Coins: Rare coins, collectible issues, and specialty products do not automatically qualify. Section 408(m) excludes specified eligible coins and qualifying bullion from the collectible classification under stated conditions.
What Makes Gold IRA Coins and Bars Eligible?
Gold IRA coins and bars must satisfy Internal Revenue Code Section 408(m)(3), including applicable coin specifications, bullion purity standards, and trustee possession requirements. Not every gold coin or bar qualifies for tax advantaged IRA treatment.
The requirements for eligible Gold IRA coins and bars are listed below.
Don't Choose Blindly
Selecting the right Gold IRA company is crucial for your retirement. Use our comprehensive comparison checklist to evaluate providers and make the best decision for your financial future.
Get Your Checklist- Gold Fineness Requirement: Gold bullion must meet the minimum fineness standard of 99.5% purity, subject to statutory exceptions.
- Eligible Gold Coins: American Gold Eagle coins qualify under a specific statutory exception, despite their gold content falling below the standard bullion purity threshold.
- Product Verification: Each coin or bar requires verification against applicable IRS requirements before purchase.
- Trustee Possession: Qualifying IRA metals must satisfy applicable trustee custody requirements to maintain compliance with federal tax law.
Are Gold Coins Eligible for a Roth IRA?
Yes, qualifying gold coins are eligible for a Roth IRA when the coins, custody arrangements, and storage meet federal tax requirements. Internal Revenue Code Section 408(m)(3) establishes the eligibility standards for precious metals held in an IRA. Roth IRA status does not remove trustee possession requirements or permit unrestricted home storage. The account’s tax treatment follows Roth IRA rules, while eligible gold investments remain subject to federal restrictions. A qualified Roth Gold IRA provides a structure for holding eligible precious metals in a retirement account.
How can you Transfer Gold Into a Gold IRA?
Transferring gold into a Gold IRA requires an eligible retirement account, a compliant funding method, qualifying precious metals, and proper documentation. Direct trustee to trustee transfers differ from indirect rollovers in fund handling and applicable deadlines.
To transfer gold into a Gold IRA, follow the six steps below.
- Verify Account Eligibility. Confirm that the existing retirement account permits a transfer or rollover into a self directed IRA that supports precious metals.
- Choose a Transfer Method. A direct trustee to trustee transfer moves funds from one financial institution to another without distributing the money to the account holder. An indirect rollover involves receiving a distribution and depositing eligible funds into another retirement account within the applicable 60 day deadline.
- Check Deadlines and Tax Rules. Missing the rollover deadline or exceeding applicable rollover limits risks taxes and potential early distribution penalties. Direct transfers typically avoid the 60 day rollover deadline.
- Submit Required Documentation. Provide account details, transfer forms, and any documents requested by the current provider and receiving custodian. Accurate paperwork helps prevent processing delays and errors.
- Purchase Eligible Gold. Once the funds arrive, instruct the custodian to purchase gold coins or bullion that satisfy IRS eligibility requirements.
- Arrange Compliant Storage. Confirm that the metals follow applicable IRA custody and storage rules. The custodian maintains account records and coordinates the approved storage arrangement.
How Does a Gold IRA Transfer Differ From a Rollover?
A Gold IRA transfer moves retirement funds directly from one trustee or custodian to another, while an indirect rollover sends a distribution to the account owner before redeposit into an eligible retirement account. A direct trustee to trustee transfer avoids the 60 day rollover deadline because the account owner does not receive the funds. An indirect rollover requires eligible funds to be deposited into another qualifying retirement account within 60 days to avoid potential tax consequences. Eligible distributions from employer sponsored retirement plans paid directly to the participant are subject to 20% federal income tax withholding. IRA distributions follow separate withholding rules. Properly completed transfers and rollovers generally avoid immediate taxation, but missed deadlines or ineligible transactions risk taxable income and additional penalties, depending on the account holder’s circumstances.
How Gold Performed During Every Stock Market Crash
See the data: when stocks dropped 19.4% in 2022, gold only fell 4.3%. Compare gold's downside protection across decades of market volatility and economic crises.
Compare Crash PerformanceChecking account eligibility, transfer paperwork, and applicable deadlines before moving funds helps reduce processing errors and unexpected tax liabilities.
What Are the Risks of Using a Home Storage Gold IRA Company?
The risks of using a home storage Gold IRA company include custody violations, prohibited transactions, tax liabilities, misleading compliance claims, and undisclosed fees. A company’s promises do not establish compliance because the actual account structure and handling of IRA owned metals determine the tax consequences. IRA assets must satisfy federal trustee requirements, and personal possession of IRA owned gold does not automatically meet those standards. Improper control or personal use of IRA assets risks violating Internal Revenue Code Section 4975, potentially causing the account to lose its IRA status. Noncompliance also risks taxable distributions and additional taxes. Promotional claims such as “IRS approved home storage” do not replace a legal assessment of the proposed arrangement. Setup charges, annual administration, storage, shipping, and termination fees affect total costs, making a review of written agreements and fee schedules necessary before opening an account.
How Can You Evaluate a Gold IRA Company’s Storage Claims?
Evaluate a Gold IRA company’s storage claims before transferring funds or purchasing metals. Verify the following details through official records, written agreements, and independent professional advice.
To evaluate a Gold IRA company’s storage claims, follow the six steps below.
Plan Your Gold IRA Distributions Strategically
Calculate which ounces to sell, when to take distributions, and how to minimize tax impact. Get your personalized RMD strategy based on current gold prices and IRS tables.
Create My RMD Plan- Custodian Credentials. Confirm the named custodian’s legal identity and eligibility to administer the proposed IRA. Ask which institution holds the account and controls the assets.
- Legal Structure. Request written details explaining who owns the metals, who holds them, and how the arrangement complies with federal retirement account rules.
- Depository Arrangements. Identify the proposed depository, confirm the storage agreement, and review insurance coverage, inventory procedures, and withdrawal conditions.
- Fee Disclosure. Obtain a written breakdown of account setup, annual maintenance, storage, transactions, shipping, and account closure charges.
- Account Documentation. Review the IRA agreement, purchase documents, custody terms, storage contract, and distribution procedures before signing.
- Independent Tax Review. Ask a qualified tax professional or retirement account attorney to assess the specific arrangement rather than relying on the seller’s assurances.
Does a Gold IRA Provider’s Storage Guarantee Ensure IRS Compliance?
No, A provider’s storage guarantee or marketing statement does not establish IRS compliance. Federal tax treatment depends on the account structure, trustee arrangements, asset possession, and transactions involved. Internal Revenue Code Sections 408 and 4975 address IRA custody requirements and prohibited transactions. Investors need to review the written custody agreement and verify the proposed storage arrangement against applicable federal law. Independent legal or tax advice helps assess the actual arrangement before funds are transferred.
What Should You Know About US Money Reserve and Gold IRA Storage?
U.S. Money Reserve offers precious metals IRA services through a self directed IRA, a qualified custodian, and an approved depository. Its official website identifies Equity Trust Company as its preferred custodian and A-M Global Logistics as its preferred depository. The published process describes shipping purchased metals to an approved depository rather than personal home storage. The company’s published promotions include storage and maintenance fee offers subject to eligibility conditions. The current offer details specify a minimum precious metals rollover of [$200,000] for lifetime fee coverage, effective April 1, 2026, with annual covered fees capped at [$300]. Special service charges and shipping or transit insurance fees are excluded. Review the account agreement, custodian relationship, depository contract, and full fee schedule before opening an account. Company marketing describes its services but does not replace independent legal or tax guidance about US Money Reserve.
How Can You Verify US Money Reserve’s Gold IRA Storage Options?
Verify U.S. Money Reserve’s current storage options through its official IRA materials and the agreements supplied before account funding. Confirm that the proposed IRA uses an eligible custodian and request written documentation explaining the account structure, asset custody, and responsibilities of each institution. Review the custodian’s official records to verify its role in account administration and precious metals custody. U.S. Money Reserve identifies A-M Global Logistics as its preferred depository in its published IRA setup materials. Request the depository’s legal name, storage terms, insurance coverage, inventory procedures, and distribution conditions before authorizing a purchase.
Review the current fee schedule and promotional conditions to confirm the minimum account or rollover amount, annual fee limits, excluded charges, and offer expiration dates. Compare company statements about home storage against IRS guidance and obtain an independent tax or legal review before relying on claims about compliance. Official company materials explain the services offered, but the actual account agreements and applicable federal law determine whether a proposed storage arrangement satisfies IRS requirements.

One More Thing...
If you're serious about protecting your retirement, get the complete Gold IRA guide. It's free, there's no obligation, and it could be one of the smartest financial decisions you make.
Get Your Guide